Most Companies Are Using AI to Improve Their P&L. The Bigger Prize Is to Change It.
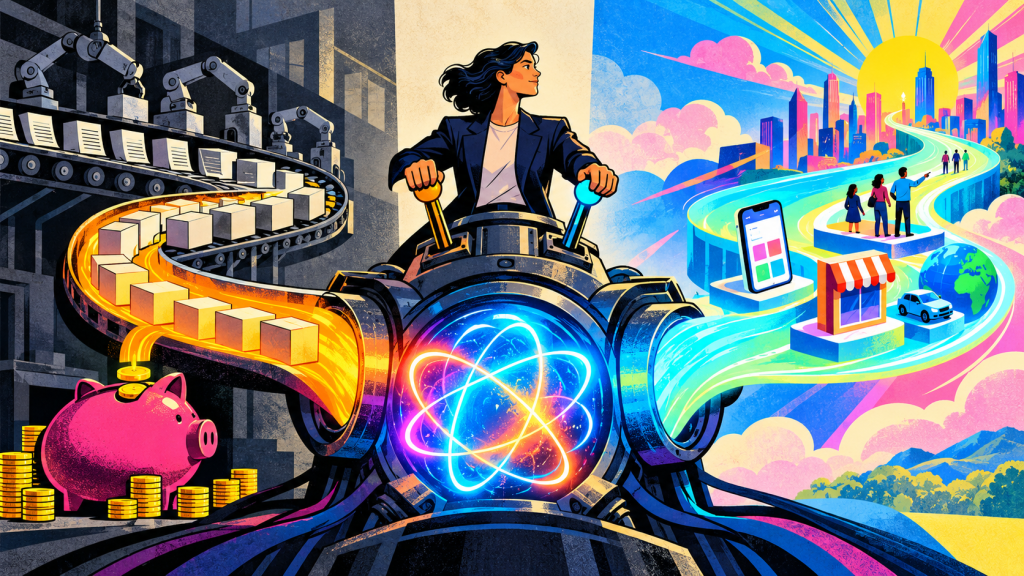
Efficiency AI protects enterprise value. Opportunity AI creates it.
Efficiency AI improves the economics of the business you already have. Opportunity AI changes what you can sell, whom you can serve, and where you can compete. Most enterprises are investing heavily in the first and calling it AI transformation.
I run engineering, which means I have been living with AI agents as working members of the organization longer than most of my peers. Agents now open pull requests, triage incidents, run their own tests, and work through backlogs overnight. Engineering was the first function where AI started doing real work at real scale, and what we learned there is a preview of what every function, and every board, is about to confront.
The Moment Every Executive Team Will Hit
Almost every executive team now has an AI strategy, and underneath, most of them look the same. Reduce cost. Increase productivity. Automate workflows. Improve developer velocity. Handle more customer inquiries with fewer people.
These are legitimate investments. I have sponsored many of them, and they pay back. But we should be precise about what they are. They are efficiency investments, not transformation.
When we put agents in front of our engineers, the gains were real and fast. Routine work disappeared. Test coverage went up. Migrations that had sat on the roadmap for years became tractable in weeks. Then, a few quarters in, a harder question arrived in an operating review: we have meaningfully more capacity, so what are we doing with it?
In most organizations the honest answer is “more of the same.” More tickets closed, more features shipped, more internal tooling. Output goes up and to the right. It is not obvious that the business does.
That moment, with productivity clearly up and value unclear, is the gap between Efficiency AI and Opportunity AI. Every function will hit it. Engineering simply hit it first.
Efficiency AI Is a Margin Story
Efficiency AI starts with something the company already does. A process, a cost, a workforce, a service. AI improves the economics.
A support interaction costs $15, and AI brings it to $5. A feature that took six weeks ships in three. A team that spent thousands of hours on document review now has an agent do the first pass.
The business case is easy to write because there is a baseline. You can calculate cost reduction, cycle time, capacity released, and margin expansion. These are large numbers and they deserve disciplined pursuit.
But there is a ceiling. Your competitors have access to the same models and the same agents, often on the same day you do. The advantage from adopting first is real and temporary. Today’s edge becomes tomorrow’s operating standard, and your customers eventually expect it to show up in your price, speed, or service.
That makes Efficiency AI comparable to cloud adoption or ERP modernization: mandatory, expensive to be late on, and not a source of lasting differentiation.
Efficiency advantage tends to become industry efficiency. Executives should be careful not to confuse a productivity improvement with a durable competitive position.
Opportunity AI Is a Growth Story
Opportunity AI starts from a different question. Not “how can AI make this activity cheaper,” but:
What becomes economically possible now that expertise, and increasingly the work itself, has become dramatically cheaper?
Suppose your company provides expert advice, and high-touch advisory was only viable for your largest 1,000 customers. An agent-backed version of that expertise might serve 100,000. That is not a 30% productivity gain. It is market expansion.
Suppose you sell software that helps customers interpret complex information. Today the customer still has to decide what to do with it. An agent could continuously analyze their situation, recommend actions, carry out the approved ones, and learn from the results. You have moved from software that informs work to software that performs work, and with it your pricing, positioning, and competitive set.
Or suppose there is a service you have never offered because it required thousands of hours of specialized expertise. If agents bring that cost down far enough, the service becomes viable. Nothing was automated. A new revenue pool was created.
This is where the engineering experience becomes a business asset. The organization that has learned to build with agents is the one best positioned to build agents into the product and sell them to customers who could never buy that capability before.
The Capital Allocation Mistake
Most enterprises put all of these ideas into one AI portfolio and one funding process. That is the mistake, because the two have different economics.
Efficiency AI has a measurable baseline. Opportunity AI usually has none: no current revenue because the product does not exist, no efficiency baseline because nobody does the work today, no demand history because no customer has been offered the capability.
Put both through the same ROI process and efficiency wins almost every time. Picture two proposals competing for funding:
We can automate this process and save $8 million over three years.
Agents may let us create a new service category. We believe customers will pay for it, but we need six months to find the business model.
Which survives the CFO review? Usually the first, and rationally so if both are judged by the same framework.
This will become one of the defining failure modes of enterprise AI: companies will systematically overfund measurable efficiency and underfund uncertain opportunity. Not for lack of imagination, but because the capital allocation machinery favors optimization over exploration.
The two therefore need two value equations.
For Efficiency AI: Existing Revenue − Lower Cost = Higher Margin.
For Opportunity AI: New Capability × Willingness to Pay × Addressable Market = New Enterprise Value.
The second is less predictable and it is where outsized returns live. Efficiency AI adds points of operating margin. Opportunity AI creates a category, opens a market, changes retention, or changes the growth rate. Capital markets value those outcomes very differently. Taking out $20 million of cost creates real value. Finding a repeatable $200 million revenue line changes the growth story.
This is not a technology distinction. It is a corporate strategy distinction, and it belongs on the board agenda.
AI Changes the Economics of Expertise
Opportunity AI matters so much because it attacks a constraint that has shaped business models for a century: expertise does not scale cheaply.
Doctors cannot see unlimited patients. Lawyers cannot review unlimited contracts. Advisers cannot give bespoke advice to every household. That scarcity is why companies segment customers: premium customers get high-touch service, everyone else gets a standardized experience, and some segments are never served at all.
When expertise is available at a dramatically lower marginal cost, a business can reconsider which customers it serves, what service levels it offers, and which products it can profitably build. That is why the most valuable AI opportunities will not look like automation projects. They will look like business model redesign.
The Capacity Trap
There is a second lesson from engineering that applies everywhere.
When agents gave our engineers substantially more capacity, we did not automatically create more value. The temptation is to produce more: more features, more services to maintain, more surface area to secure. When the cost of producing work falls, the cost of producing the wrong work does not fall with it. It shows up later as complexity and as products nobody asked for.
The bottleneck moved quickly, away from building and toward deciding what to build, specifying it well, and judging whether it solved a customer problem. Productivity is only valuable when the added capacity is pointed at valuable problems.
For a CEO, this is the organizational consequence of AI that matters most: the scarce resource is no longer the ability to make things. It is the judgment to decide what deserves to exist.
What This Demands of Technology Leaders
The technology executive’s job is changing accordingly, and I would argue in three ways.
From delivery to capital allocation. The technology leader has to be able to stand in front of the CFO and the board and say which AI investments are operating leverage, which are options on growth, and why the portfolio needs an explicit split. Decide what share of the capacity agents release goes back into the existing roadmap and what share funds new bets. If leadership does not decide, the backlog will, and the backlog always chooses efficiency.
From measuring output to measuring outcomes. Throughput was a weak proxy before agents and is a misleading one now. The measures that matter are time to customer value, quality in production, and the business results each team owns.
From controls to enablement. Agents that act inside production systems, and eventually on behalf of customers, need permissions, audit trails, evaluation, and clear human checkpoints. Done well, that governance is what lets the company say yes to Opportunity AI with confidence. Done poorly, or not at all, it is what forces the company to say no.
Two Portfolios, Two Scorecards
Because the value models differ, the metrics must differ.
Efficiency AI should be measured on cost to serve, hours eliminated, cycle time, quality, and margin improvement.
Opportunity AI should be measured on customer adoption, willingness to pay, new revenue, market expansion, experiments completed, and time to learning.
The first is an optimization portfolio. The second is an options portfolio, and it should be run like one: fund inexpensive experiments, look for customer evidence quickly, double down when it appears, and kill ideas when it does not. Some of these bets should fail. If every one succeeds, the company is not exploring far enough from what it already knows.
Agents make this far cheaper than it used to be. A small team can take an idea from concept to a working product in front of real customers in days rather than quarters. The cost of being wrong is falling, and an organization whose cost of being wrong is falling should be exploring more.
Efficiency Funds Opportunity
The best companies will not choose between the two. They will build a flywheel.
Use agents to remove low-value work. Capture the productivity and lower the cost base. Then deliberately reinvest part of that capacity and part of those savings into new products, services, and business models.
Efficiency becomes the funding mechanism for exploration. That is a far more compelling AI strategy than a collection of copilots and automation projects, and it gives the CFO and the technology organization a shared language: some investment buys predictable operating leverage, some buys asymmetric options on growth, and the portfolio needs both.
Five Questions for the Board
If I were sitting across from a board or a CEO this quarter, these are the questions I would want answered:
- What share of our AI portfolio is efficiency, and what share is opportunity? Most companies will find it is 80% to 90% efficiency.
- Which of our AI initiatives could change our pricing model, our addressable market, or our competitive set, rather than our cost base?
- Do efficiency and opportunity investments go through the same approval process? If so, what have we killed that should have been an experiment?
- Where is the capacity agents have released actually going?
- Who owns the decision about what deserves to exist?
The Strategic Question Has Changed
For the past few years executives have reasonably asked how much productivity AI can deliver. We should keep answering that question. But another deserves equal time in the boardroom:
What revenue, customers, products, or markets become possible because AI changed the economics?
Engineering leaders have a particular responsibility here. We put agents to work first. We have seen what they can do, where they break, and what it takes to run them safely. That experience should not stay inside the engineering organization as a productivity story. It should shape how the company thinks about what it can become.
Efficiency AI improves the business you have. Opportunity AI creates options on the business you could become.
The first is the price of competing. The second is where outsized value will be created.
So the real question for executive teams is no longer how much money AI can save.
It is how much new enterprise value we are willing to use AI to go create.